Germany · taz · · 1h
Retirement at 63: A question of justice
Deutsch (original) · Auto-translated to English
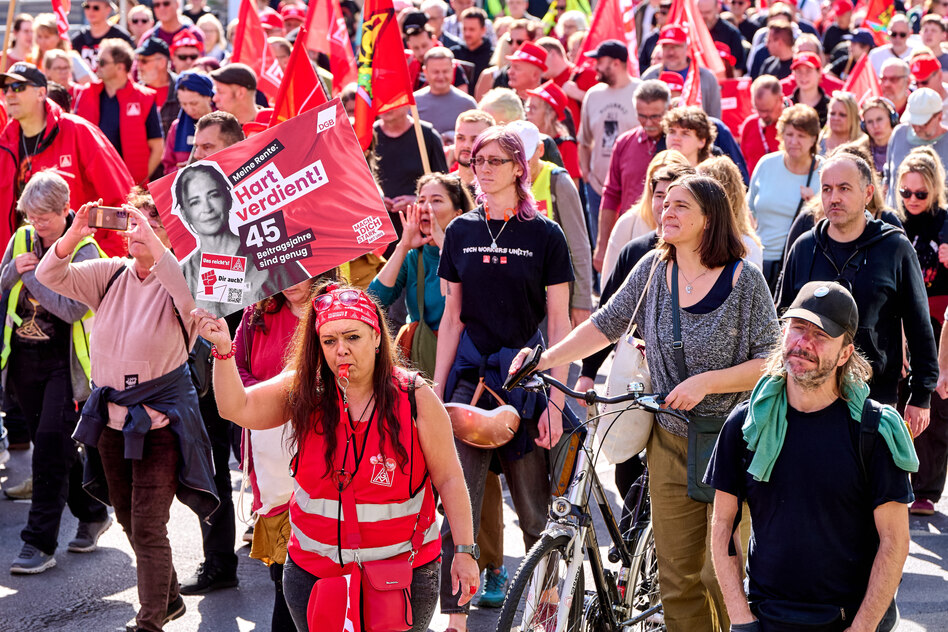
Some political benefits already have their recipients in their names. Agricultural diesel, mother's pension, the reduced tax rate for the catering industry: everyone can see who is being considered here. Things are different when it comes to “retiring at 63”. You only recognize who it favors at second glance.
It starts with the name. The 63 only applied to the first years of birth, for everyone born in 1964 and above the limit is 65. The actual condition remains: 45 years of insurance. Anyone who fulfills this requirement can retire without deductions up to two years before the standard retirement age. Anyone who narrowly misses it but wants to leave at the same time will pay discounts of up to 7.2 percent for life.
researches and teaches at the University of Bayreuth, among other things, on the economics of old-age security and has presented his own reform proposal, the ResilienzRente. His main job is as an executive assistant at the Bayerische insurance group.
Frank Hoffer himself finds this regulation unfair in his taz guest commentary “The capital pension doesn’t work either”. Nevertheless, he only wants to end it after five years of transition: the savings are small, the political price is high. The only question is, for whom? Because the question of distribution begins where some people are allowed to access it longer than others.
Let's imagine the state pension as an all-you-can-eat buffet. Admission depends on income: those who earn more pay more and get a bigger plate in return. Basically a VIP ticket. Sounds fair. You eat until you leave.
The catch: Guests with the VIP ticket stay seated significantly longer. They live longer and go to the buffet more often. They end up eating measurably more per euro of entry than the guest with a small ticket who has to leave earlier.
And the pension at 63? Open the door earlier to those who stay the longest. No extra charge. The boys stand in line outside, paying more for the smaller plates and wondering what will be left when they are finally allowed to go to the buffet.
The picture stands up to the statistics. According to the German Institute for Economic Research (DIW), anyone who takes advantage of the pension at 63 has an average of 47 earnings points instead of 30. According to the Pension Commission, the average pension is 1,677 euros, around a third higher than the pension of long-term insured people with discounts.
The taz is an independent, left-wing and opinionated daily newspaper. We have been arguing in our comments, essays and debate texts since the taz was founded in 1979. We often cannot and do not want to agree on an opinion. That's why you'll find some completely opposing positions here - all part of the very broad left-wing spectrum of opinions.
The commission names the beneficiaries themselves: higher earners, healthier people, men. And those who earn better live longer: for West German men, the top and bottom tenth of lifetime income at 65 are separated by around 7 years of life expectancy. The statutory pension redistributes here, from bottom to top. And the pension at 63 adds two years on top.
In doing so, it honors a pattern that is often sold as an effort: completeness. However, those who have been in mini-jobs for a long time, have been incapacitated for a long time or have been unemployed have gaps. The 45 years are a threshold that needs to be overcome. And those who have never stumbled are more likely to cross thresholds.
The regulation also does not measure wear. Retirement at 63 does not differentiate between office chairs and roof structures. If you want to protect those who are worn out, you need the health-tested hardship regulation that the Commission is proposing.
The Commission's reform package demands the most from younger people anyway: two additional contribution points for capital coverage and longer periods of employment. The protest only became loud when a single measure was supposed to affect the strong vintages themselves. Hoffer also gives the reason: the cut affects the SPD's core skilled worker electorate. A more honest sentence about clientel politics has not been written for a long time.
But you don't just pay with money. According to DIW, without the regulation, those affected would retire around ten months later, around 125,000 more full-time employees per year. A country that complains about a shortage of skilled workers subsidizes the early exit of healthy, high earners. The baby boomers are defending an exception whose bill is paid by their children, who themselves grow old in worse conditions.
Hoffer's objection remains: the savings potential is small, and the costs of a transition are ultimately peanuts. But a privilege is not measured by what its abolition saves. Justice has no minimum amount. And even from a fiscal perspective, the benchmark is not correct. The savings arise over lifelong discounts. But Hoffer is counting on the start-up: He compares the savings in the first year with the ongoing costs of capital coverage. The DIW puts the 1957 vintage alone at 9.5 billion over the full reference period, and it expects the same for subsequent vintages. And Hoffer's transition? According to our own figures, it costs a good 27 billion. Peanuts turn into quite a few nuts, year after year.
Hoffer's strongest argument, however, is predictability. Anyone who has been paying in for decades needs to know when and under what conditions the pension will be paid out. Agreed. But: What is the rule here, what is the exception?
Since the pension reform in 1992, the rule has been in effect: those who leave early pay deductions. In 2007, the exception came after 45 years of insurance, as a concession for the pension at 67, with no deductions from 65. In 2014, it was reduced to 63 within a few months, and in 2023 it was expanded to include free additional income. It was always expanded quickly, but will only be dismantled very slowly.
Five years of transition from 2027 mean: those born up to 1966 will still be eligible for deductions. These are the years with the highest birth rates in this republic. Savings would only be made for the smaller vintages afterwards. The transition period would be a free pass for the baby boomers. Retiring at 63 was an exception, a well-intentioned remnant of better times. Ending this exception as quickly as possible is not an imposition, but rather a return to reason.
Nevertheless, anyone who has 35 years of insurance can still retire earlier. But with the same discounts as everyone else: 3.6 percent per year. Protection of legitimate expectations should apply to everyone who meets the requirements within twelve months of the legislative resolution. For everyone else: A political prospect is not a lifelong guarantee.
If we are really serious about justice, we have to abolish the tax-free pension at 63. Not someday, but now.
Read the full story at the source
Source: taz