Politics Jacobin
The Volkswagen Crisis Exposes Germany’s Industrial Decline
A proud symbol of German industry, Volkswagen enjoys far-reaching government support. Yet as it leans on the Chinese market, it’s far from clear that the firm is going to save jobs at its German sites
English (original) ·Read in Deutsch ⇄
On October 9, European Union Trade Commissioner Maroš Šefčovič announced an agreement on hybrid vehicles, following two days of talks with Chinese Commerce Minister Wang Wentao in Beijing. According to Šefčovič, over the next four years or so, Chinese exports of full and plug-in hybrids to the EU are expected to fall below half of previous forecasts. The specific quotas, minimum prices, or monitoring mechanisms were not disclosed. The agreement is provisional, with further talks scheduled for 2027.
Shortly before Šefčovič’s trip, German Chancellor Friedrich Merz and French President Emmanuel Macron had been putting pressure on the European Commission. In early October, in a letter to Commission President Ursula von der Leyen and a joint paper, they called for the commission to be given more powers to act against market distortions by non-EU countries. A new instrument would allow companies, or even entire countries, to be excluded from the EU’s single market in serious cases. The paper names plug-in hybrid vehicles as one of such a potential case. Neither document mentions China by name, but the initiative is mainly aimed at Beijing.
For Germany’s Merz, a lot is at stake politically. According to recent polling, his Christian Democrats (CDU, plus their Bavarian ally, the Christian Social Union) now enjoy just 19 percent support, 11 points behind the far-right Alternative für Deutschland (AfD). The looming loss of tens of thousands of jobs at German automakers, led by Volkswagen (VW), and possible plant closures would further weaken his position.
Merz himself has cast the issue in fundamental terms. “Germany must remain an industrial country!” he told a CDU rally in Langenhagen near Hanover in early September, shortly after Volkswagen’s supervisory board approved its restructuring plan. “We are currently losing industrial jobs on a large scale.” No German state, he added, “is shaped as strongly by one large industrial company as Lower Saxony.” Olaf Lies, the Social Democratic premier of Lower Saxony, which holds 20 percent of the voting rights in Volkswagen, promised that “the Volkswagen sign should stay on the plants” in Emden, Hanover, and Zwickau.
Rising in the polls, the AfD presents the crisis in the auto industry as proof of the government’s failure. Its coleader, Tino Chrupalla, called the possible end of “traditional German car plants” “the result of a failed economic and energy policy” and blamed it on a “one-sided and premature fixation on electromobility.” His conclusion: “Zwickau must remain a car city beyond 2031!” In France, meanwhile, some four hundred thousand people work in vehicle and parts manufacturing.
Beyond its specific subject matter, the joint initiative by Merz and Macron is also meant to demonstrate that the Franco-German partnership within the EU is working again, after having frequently stalled in recent times. What’s less clear is whether this show is going to have its intended effects.
Protectionism
As early as October 2024, the EU had imposed countervailing duties of up to 35.3 percent on electric cars built in China, in addition to the regular 10 percent import duty. Hybrid vehicles were not subject to these duties. Since January, manufacturers have been able to avoid the duties if they commit not to sell an electric car in the EU at a price below a specified minimum. Yet none of this has slowed the influx: according to the industry group Chinese Passenger Car Association, China exported 490,000 plug-in hybrids to the EU in the first eight months of this year, 179 percent more than in the same period last year, and 630,000 fully electric cars, an increase of 49 percent.
Not all of these carry Chinese brands; exports from China also include models built there by Western manufacturers. For comparison, according to the European Automobile Manufacturers’ Association (ACEA), around 1.64 million fully electric cars and 758,000 plug-in hybrids were newly registered in the EU between January and August, accounting for 21.7 and 10 percent of the market, respectively. Chinese brands accounted for about a quarter of plug-in hybrid registrations in the EU in the first half of the year, and a reported 14.2 percent of fully electric car sales in Western Europe’s eighteen largest markets up to May. In August, Chinese-owned carmakers, including Geely’s Volvo, sold 10.8 percent of all new cars in the EU, up from 6.6 percent a year earlier.
Merz and Macron’s renewed effort was a response to the weak outcome of previous measures. For example, the countervailing duty on BYD, China’s largest electric vehicle manufacturer, stands at 17 percent, or 27 percent including the regular import duty. However, even such high tariffs do not offset the cost advantage of Chinese production. At the same time, Chinese manufacturers are increasingly pushing into Europe as a price war rages in their home market and domestic sales decline. And Chinese hybrids, which are seeing the strongest export growth, were subject only to the regular import duty until the understanding reached by EU leaders last month.
On October 12, Emmanuel Macron opened the Paris Auto Show by calling for even stronger protection of the European market. On the same day, Volkswagen CEO Oliver Blume, at a joint appearance with French Industry Minister Sébastien Martin on the sidelines of the show, spoke out in favor of closer cooperation between the two countries: “Now is the moment when France and Germany, as Europe’s largest automotive nations, must work together.” He added, “I’m not talking about protectionism. Rather, I’m talking about an industrial policy driven by European interests.” Regarding Šefčovič’s negotiations, he said, “We welcome the progress made in the talks with China.”
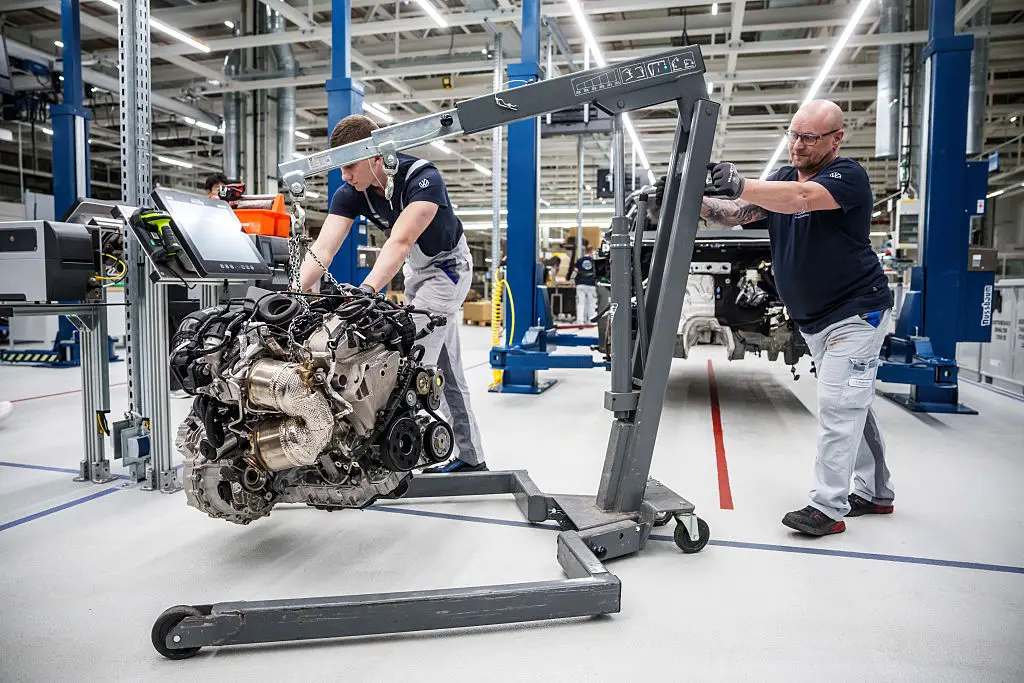
The CEO can use all the relief he can get, as Volkswagen is in crisis in Germany: On September 3, the supervisory board approved the “Future Plan 2030.” It stipulates that a further fifty thousand jobs worldwide are to be cut, with Blume estimating that about half of those will be in Germany. This adds on to a decision already made in December 2024 to cut more than thirty-five thousand VW jobs in Germany by 2030. The company says it can no longer guarantee that it can competitively use its capacity at plants in Emden, Hanover, and Zwickau, and at Audi’s Neckarsulm facility. However, no decisions on closures have been made yet. Alternatives are being explored, including the production of Chinese VW models in Germany. Among other reasons, the company cites an overcapacity of approximately five hundred thousand vehicles in Europe and competition from China.
That competition isn’t just about subsidies. In 2024, the European Commission concluded that China’s electric car industry benefits from unfair state subsidies that threaten to harm European manufacturers; this finding is the legal basis for the countervailing duties. But in reality, China’s strength does not rest on subsidies alone. Chinese manufacturers have also advanced technologically. Contemporary Amperex Technology Co., Ltd. (CATL) and BYD are among the world’s largest battery producers. According to consultancy McKinsey & Company, Chinese electric car makers launch new models in about twenty-four months, compared with up to forty-five months for established mass-market manufacturers. Volkswagen itself has taken a stake in XPeng to jointly develop models for the Chinese market, thereby acquiring expertise in China. Added to this is the model strategy. Chinese manufacturers are bringing affordable, compact cars to Europe; BYD’s Dolphin Surf, for example, starts at €23,490 in Germany. Volkswagen and other German manufacturers, on the other hand, have relied on high-margin SUVs and premium models for years.
Combustion-Engine Ban
As one of the first Western automakers in the People’s Republic, Volkswagen has a long history of dependence on China. In October 1984, the company signed a joint venture agreement with the state-owned conglomerate Shanghai Automotive Industry Corporation (SAIC). Mass production began in 1985: in its first year, the joint venture sold 1,684 vehicles; by 1993, that number had risen to around 100,000. In 2019, Volkswagen delivered 4.23 million vehicles there, accounting for nearly 40 percent of its global sales. In January of that same year, then CEO Herbert Diess said, “The future of Volkswagen will be decided on the Chinese market.”
While Volkswagen saw its future in China, the outlook for the internal combustion engine in Europe was in flux. In fall 2022, the European Parliament and member states agreed that, starting in 2035, only zero-emission new cars would be permitted for registration. In March 2023, German Federal Minister of Transport Volker Wissing called into question Germany’s previously given approval; the law was finally passed at the end of the month only after a commitment to electrofuels was secured.
Manufacturers, too, made commitments and in some cases backtracked on them: Volkswagen announced in 2021 that it would phase out internal combustion engines in Europe between 2033 and 2035. Mercedes-Benz had declared in 2021 that it would sell only electric cars wherever possible by the end of the decade but abandoned this goal in 2024. At the end of 2025, the European Commission proposed scaling back the 2035 target to a 90 percent reduction in CO2 emissions.
China, on the other hand, has pursued a consistent policy for years: from 2010 through the end of 2022, the government paid manufacturers subsidies for every electric or plug-in hybrid vehicle sold in the country, and the “Made in China 2025” strategy designated electric mobility as a key industry. This support may have distorted market competition, but it gave the country’s manufacturers planning certainty. Europe, by contrast, has put its car industry at a disadvantage with its political flip-flopping.
Now Volkswagen is also coming under pressure in China: in the third quarter of 2026, the company delivered 405,800 vehicles there, 38.5 percent less than a year earlier. Globally, the decline was 14.3 percent. Volkswagen is thus facing three simultaneous developments: sales in China are falling; the company is increasingly sourcing technology from Chinese partners; and in Europe, the EU is protecting the market from Chinese imports, including vehicles from Volkswagen’s own Chinese plants, with tariffs, minimum prices, and volume agreements.
The pressure on Berlin’s political leaders to stand by its carmakers is considerable, and the government has responded. Since May, buyers of electric cars have been able to claim a state bonus of up to €6,000; plug-in hybrids also qualify. The program is funded with €3 billion until 2029. Yet because eligibility does not depend on where a car is made, Chinese models also benefit. Merz has also campaigned against the EU’s planned ban on new combustion-engine cars from 2035, which matters greatly to German manufacturers. “We will no longer hold on to this stubborn and wrong ban on combustion engines in the European Union,” he told a CDU party conference in late November 2025.
Last month, Berlin and Paris agreed on a joint position: a 90 percent cut in new cars’ CO2 emissions by 2035, without requiring the remaining 10 percent to be offset. Two committees of the European Parliament have since backed a 95 percent compromise, with additional allowances for European green steel; the plenary is due to vote in December. The political pressure is also coming from German states. In July, Lower Saxony’s Social Democratic premier, Olaf Lies, wrote to Commission President Ursula von der Leyen, Merz, and Vice Chancellor Lars Klingbeil calling for tariffs on hybrids from China.
Yet it’s also clear that support for the car industry is not the same as support for German jobs. By the end of June 2027, Volkswagen plans to present a strategy for its European production, which will also determine the future of its plants in Emden, Zwickau, Hanover, and Neckarsulm. The German government faces the question of whether the interests of a corporation that manufactures in China and exports from there to Europe still align with those of its German sites and their workers.
This article originally appeared in Jacobin, a democratic socialist magazine publishing long-form essays and analysis on politics, economics, and culture. Subscribe to the print edition for $20 a year.